Merchant account: What it is, how it works, and how to secure yours
Payments 101
Updated 6 Nov 2026
10 min
Andrii Stoikov
Head of Support, Integration, Billing Operations, Solidgate
Businesses that accept cards hear acquirer, PSP, MID, and reserve long before anyone explains how they fit together. Here’s what’s worth knowing about merchant accounts.
Card payments land in a merchant account first. The funds reach your business bank account only when the acquirer or payment provider pays them out.
A business merchant account comes from an acquiring bank or a PSP, and its terms decide what each payment costs, how long part of your revenue stays in a rolling reserve, and whether the provider can close it. Those terms differ between a dedicated account held with an acquirer and an aggregated account under a payment facilitator.
This guide explains what a merchant account is, how a payment reaches it, which types and costs to expect, how to get one, and how to keep it.
TL;DR
- A merchant account holds card payment funds until payout to your business bank account, under an agreement with an acquiring bank or PSP
- Dedicated accounts give you your own MID and a direct acquirer contract, and aggregated accounts place you under a payment facilitator’s agreement
- Costs combine per-transaction fees and account-level fees, and some agreements add a rolling reserve that holds part of your revenue for 30 to 180 days
- Getting an account takes seven steps, from defining requirements to taking the first payment, with underwriting that usually takes a few days to a few weeks
- Visa’s and Mastercard’s fraud and dispute thresholds drive account closures, and a termination raises scrutiny on the next application
What is a merchant account?
A merchant account is a specialized account that holds card payment funds until they are paid out to your business bank account. Businesses set one up under an agreement with an acquiring bank, either directly or through a payment service provider (PSP).
Merchant accounts let businesses accept payments from customers, mainly by debit and credit card and through other electronic payment methods.
Merchant account vs business bank account
A merchant account and a business bank account do different jobs. Merchants use a business bank account for all aspects of business operations, such as paying employees and covering rent and website expenses. A merchant account only holds funds from customer sales and pays them out to your main business bank account.
How a merchant account works in a transaction flow
A card payment reaches your merchant account only after it passes through:
- Processor
- Issuing bank
- Acquirer
It starts when the customer taps, swipes, or inserts the card at the POS (point of sale), or enters the card details at online checkout. The payment goes to the merchant’s credit card processor, which then contacts the issuing bank via the credit card network.
The issuing bank confirms that the customer is authorized to make the payment and has enough funds or credit to cover it. If so, it approves a funds transfer for that amount. The merchant then captures the approved transaction, the card network clears it to the issuer, and the issuer settles the funds with the acquirer.
The acquirer then deposits the funds into the merchant account. The merchant holds that account under its agreement with an acquiring bank or PSP, and it acts as a temporary holding place for the funds.
The acquirer or PSP pays the funds out to the merchant’s actual business bank account only after they reach the merchant account. Payout follows the schedule in the merchant’s agreement.
A split the work of passing card data from checkout and moving the transaction through the card network to the issuer. The merchant account sits apart from both and holds the resulting funds until payout.
Types of merchant accounts: Dedicated and aggregated
Merchant accounts come in two contract structures, dedicated and aggregated, and a business can hold several of either.
Dedicated merchant account. A dedicated account gives you your own merchant ID (MID) and a direct contract with an acquirer. The acquirer underwrites your business before approving it, and you agree terms with the acquirer directly. Underwriting usually takes a few days to a few weeks.
Aggregated merchant account. An aggregated account places you under a payment facilitator’s (PayFac) agreement with its acquirer. The facilitator onboards you through its own process, so you do not need a separate acquirer contract. Your terms follow the facilitator’s agreement.
| Dedicated merchant account | Aggregated merchant account (PayFac) | |
| Who holds the contract | You contract directly with an acquirer | The payment facilitator holds the agreement with its acquirer, and you are a sponsored merchant under it |
| Merchant ID (MID) | Your own MID | Typically operates under the facilitator’s registration instead of an acquirer-issued MID of your own |
| Onboarding | Acquirer underwriting, usually a few days to a few weeks | Follows the facilitator’s own onboarding process |
| Control over terms | Terms agreed directly with the acquirer | Terms set by the facilitator’s agreement |
| Typical fit | Businesses that want their own acquirer relationship and merchant ID | Businesses that want to accept cards under an existing facilitator agreement |
Selling online and selling across borders each add requirements to whichever structure you choose.
Online and ecommerce merchant accounts
Selling online requires an account approved for card-not-present payments, where the card is not physically present at checkout. Card-not-present sales carry higher exposure to fraud and disputes because the merchant cannot verify the card in person.
3D Secure adds issuer authentication to these payments and can shift fraud liability to the issuer on authenticated transactions. Visa’s VAMP (Visa Acquirer Monitoring Program) ratio counts card-not-present transactions only, which places online businesses inside its scope.
International merchant account
Selling in several countries often leads to multiple MIDs, one per region, under either structure. An international merchant account lets a business accept cards and settle funds across more than one country or currency.
processes a payment through an acquirer in the cardholder’s own market, and cross-border acquiring processes it through an acquirer abroad. Merchants often add a local acquirer in a market where cross-border processing can hurt approval rates.
A can settle funds in several currencies, which limits conversion steps before payout. Each new acquirer relationship goes through its own underwriting, which usually takes from a few days to a few weeks.
Core insight: Merchant accounts are dedicated accounts held directly with an acquirer or aggregated accounts under a payment facilitator, and a business can hold several of either, each with its own MID. Online sales add card-not-present approval to that choice, and international sales add local or cross-border acquiring.
How much does a merchant account cost?
Merchant account fees typically fall into two groups: per-transaction fees and account-level fees.
Per-transaction fees apply to every payment and combine three charges. Interchange goes to the issuing bank and varies by card type. For instance, published US consumer schedule ranges from 0.05% + $0.21 for regulated debit to 3.15% + $0.10 for non-qualified consumer credit, effective October 2026.
Scheme fees go to the card network, such as Visa or Mastercard. Acquirer markup is the acquirer’s own margin on top of both, and a PSP adds its margin if you reach the acquirer through one. A merchant sees these fees itemized or as one blended rate, depending on the pricing model.
Account-level fees are charges for holding the account, set in the merchant account agreement. Common ones are setup, monthly minimum, PCI DSS (Payment Card Industry Data Security Standard) compliance, and early-termination fees. apply per dispute and vary by provider.
Some agreements hold back part of your revenue as a , which covers chargebacks and refunds that arrive after a sale has settled. It withholds part of each transaction’s funds, typically for 30 to 180 days, then releases them. Reserved funds stay out of your cash flow until release.
Core insight: A merchant account costs interchange, scheme fees, and acquirer markup on every transaction, plus account fees. Some agreements also hold back a rolling reserve, which keeps funds out of working capital until release.
How to get a merchant account
Merchant account setup takes seven steps, from defining your requirements to taking the first payment.
Determine your business requirements
Start by defining your business requirements: target countries, , card brands (Visa, Mastercard, etc.), and the currencies you want to accept.
Consider also which payment types your business model calls for: one-time purchases, subscriptions, and repeat purchases through .
Choose a merchant account provider
A merchant account provider can be either an acquirer, which offers a dedicated account, or a PSP or PayFac, which typically offers an aggregated one. Before you open a merchant account, compare each provider’s fees, transaction rates, customer support, and other features against the needs of your business.
Fill out an application and provide all required documents
Once you’ve chosen a provider, you fill out an application. The application asks for business details:
- Incorporation documents
- Business registration
- Owner and director IDs
- Tax identification numbers
- Bank statements
- Processing history
- Description of your business model
Underwriting usually takes from a few days to a few weeks.
Undergo a KYC check
A Know Your Customer (KYC) check reviews your company’s background and risk profile. Acquirers and PSPs consider the length of time the company has been established, history of bankruptcy, past credit issues, and any previous merchant accounts.
Providers might also assess whether your business is susceptible to credit card fraud. If a provider deems a business high risk, it might initially set higher transaction fees or apply special reserve terms to offset that risk.
Get the approval and live credentials
Live credentials are private, so only the merchant who owns the account and its authorized personnel should know them. Merchant accounts typically require login credentials such as a username and password, which give access to the merchant admin panel with all necessary settings. For US accounts, the credentials can also come as a VAR (value-added reseller) sheet that lists every input needed to set up the payment gateway.
Set up the payment gateway
Once your merchant account is approved, connect it to a payment gateway so you can process payments. A PSP typically includes a gateway. With a direct acquirer account, you connect a gateway using the merchant ID and live credentials your provider issues.
Start accepting payments
Once the payment gateway is live, you can start accepting customer payments by credit and debit card. Opening a merchant account can be complex and time-consuming. Work with a provider that has a proven record of reliability when it processes your customers’ payments and handles sensitive financial information.
How to keep your merchant account secure: 2026–2027 monitoring rules
Merchants keep a merchant account by following the rules in their agreement with the payment processor or acquiring bank. Knowing why an account gets terminated helps merchants keep it in good standing and avoid interruptions to payment processing.
Visa and Mastercard each run a monitoring program that flags merchants whose fraud and dispute levels pass a set threshold.
Visa’s updated VAMP took effect on 1 April 2025. The divides fraud reports plus disputes by settled transactions and counts card-not-present transactions only. From 1 April 2026, the Excessive merchant level starts at a VAMP ratio of 1.5% and 1,500 combined fraud reports and disputes in a month. That applies in the EU, US, and other regions, and the UAE region stays at 2.2%.
Excessive Chargeback Program flags a merchant as Excessive at 100 to 299 chargebacks and a chargeback-to-transaction ratio of 1.5% to 2.99% in a month. The High Excessive tier sits above that range.
Why merchant accounts get closed
Merchant account closures can occur for a variety of reasons.
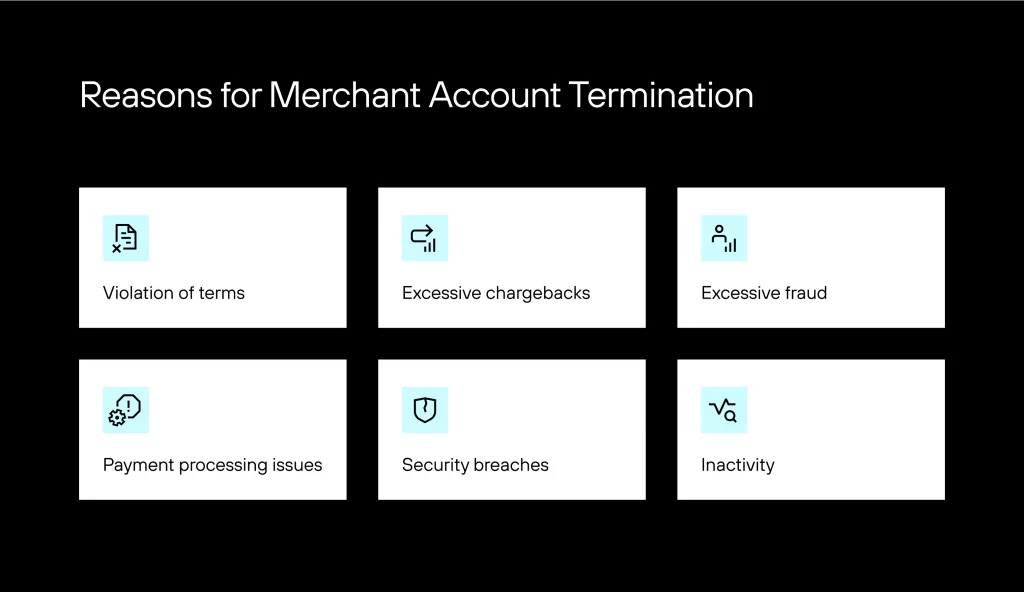
Violation of terms. If a merchant violates the terms of the agreement with its payment processor or acquiring bank, the provider can close its merchant account. This can happen if the merchant engages in fraudulent or illegal activities or violates industry regulations.
Excessive chargebacks. Chargebacks occur when customers dispute a transaction, and the customer gets the funds back. If a merchant receives excessive chargebacks, its payment processor or bank may close its account.
This can happen if customers are disputing transactions due to poor customer service, product quality issues, or other problems. Some acquirers set internal limits stricter than the card network thresholds, so a review can start before a program flags the merchant.
Mastercard’s Global Merchant Audit Program () takes effect on 1 April 2027 and folds its Excessive Fraud, Excessive Chargeback, and High Excessive Chargeback merchant programs into one framework. GMAP also counts confirmed fraud that never resulted in a chargeback. Tracking the chargeback ratio monthly against the lowest limit in the acquiring agreement shows how much headroom remains.
Excessive fraud. At Visa, issuer fraud reports and disputes feed one combined VAMP ratio, so a rise in raises the same number that chargebacks do. Pre-authorization screening rules can limit the fraud reports that reach the ratio.
Payment processing issues. Financial institutions may close the merchant account if a merchant’s doesn’t work correctly or comply with industry standards.
Security breaches. Merchants are responsible for protecting sensitive customer data, such as credit card numbers and personal information. The financial institution may close the merchant account if a security breach exposes customer data.
Inactivity. If a merchant’s account remains inactive (dormant) for an extended period, its payment processor or bank may close it. This can happen if the merchant stops using the account for processing payments or if they go out of business.
A closed account makes it harder to open a new one with another financial institution, because providers can view a history of closures negatively.
Merchant account termination and the MATCH list
MATCH (Member Alert to Control High-risk Merchants) is Mastercard’s list of merchants that acquirers have terminated, and a listing stays on record for five years. A terminated merchant account usually leaves that record for other acquirers to see. Acquirers commonly report excessive chargebacks, excessive fraud, and PCI DSS non-compliance as reasons for adding a merchant. Visa runs its own list, the Visa Merchant Screening Service (VMSS).
Acquirers check these lists during underwriting, so a listed merchant typically faces higher scrutiny and may see reserve terms on a new account. The acquirer that added a listing handles questions about that specific entry.
Core insight: A merchant account stays open when the combined fraud and dispute ratio stays under Visa’s 1.5% VAMP level and Mastercard’s 1.5% chargeback level. Any stricter limit in the acquirer’s agreement applies on top. A termination can lead to a five-year MATCH listing that raises scrutiny on the next application.
When one merchant account is not enough: Multi-acquirer setups
A single merchant account ties card acceptance to one acquirer, so an outage, a market gap, or a termination can stop payments in that market. Businesses often add acquirers for three reasons:
- Failover keeps payments running when one acquirer slows or fails
- Local acquiring covers markets where the business has no acquirer of its own
- Cost-based routing sends each payment to the cheaper eligible acquirer
Solidgate is a that connects a business to multiple acquirers, providers, and payment methods through one integration. Its sends each transaction to the connector with the highest chance of success. Cascading retries an eligible decline with the next provider in the chain, and failover reroutes traffic when a provider slows or fails.
On the same orchestration platform, businesses can add services such as billing, fraud prevention, dispute management with , and more.
to see how a multi-provider setup would work for your markets.
Frequently asked questions
A merchant account holds card payment funds between the moment a payment settles and the moment it is paid out to your business bank account. An acquiring bank or PSP provides it, and its agreement sets your fees, payout schedule, and any reserve.
Choose a provider, then apply with business documents such as incorporation papers, registration, owner IDs, tax numbers, bank statements, and processing history. The provider runs a KYC check, and underwriting usually takes a few days to a few weeks. After approval, you connect a payment gateway and take your first payment.
Yes. Card payments settle into a merchant account, which you hold directly with an acquirer or through a PSP or payment facilitator. A PSP or facilitator can supply the account under its own agreement, so you do not need a separate acquirer contract.
Acquirers hold part of your funds in a rolling reserve to cover chargebacks and refunds that arrive after a sale settles. They tend to set one up when risk looks higher, such as a new account, a high chargeback rate, or a subscription model. Funds are typically released after 30 to 180 days.
A terminated merchant can still apply for a new account. Providers can view a history of closures negatively, and acquirers check lists such as MATCH before they approve an account. Expect higher scrutiny and possible reserve terms on the new account.
A MATCH listing stays on record for five years. Mastercard stores the list of merchants that acquirers have terminated, and other acquirers can check it during underwriting. Questions about a specific entry go to the acquirer that added it, so a termination can affect applications long after the account closes.
Recent articles