Interchange fees explained: What merchants actually pay in 2026
Payments 101
Updated 25 Sept 2026
11 min
Andrii Stoikov
Head of Support, Integration, Billing Operations, Solidgate
Interchange fees quietly eat into every card payment, and the rates vary more than most merchants realize. This guide breaks down 2026 rates by region and network, and the levers that actually lower what you pay.
Behind every tap, swipe, or card insert lies a financial ecosystem most consumers never see. At the heart of this system are interchange fees – often abbreviated as "IC" – which form the foundation of card payment economics. These fees represent a significant cost for merchants while simultaneously funding the card payment infrastructure that consumers rely on daily.
For merchants , interchange fees have a direct impact on profitability. Yet the terminology, calculation methods, and pricing models surrounding interchange can seem deliberately obscure.
This article covers interchange fees and the IC++ pricing model, including 2026 rates across major markets, how regional regulation shapes what merchants actually pay, and the levers that genuinely lower your effective rate.
TL;DR
- Interchange fees are the transfer fee the acquiring bank pays to the issuing bank on every card transaction – the largest single component of card processing costs, set by card networks and non-negotiable for merchants
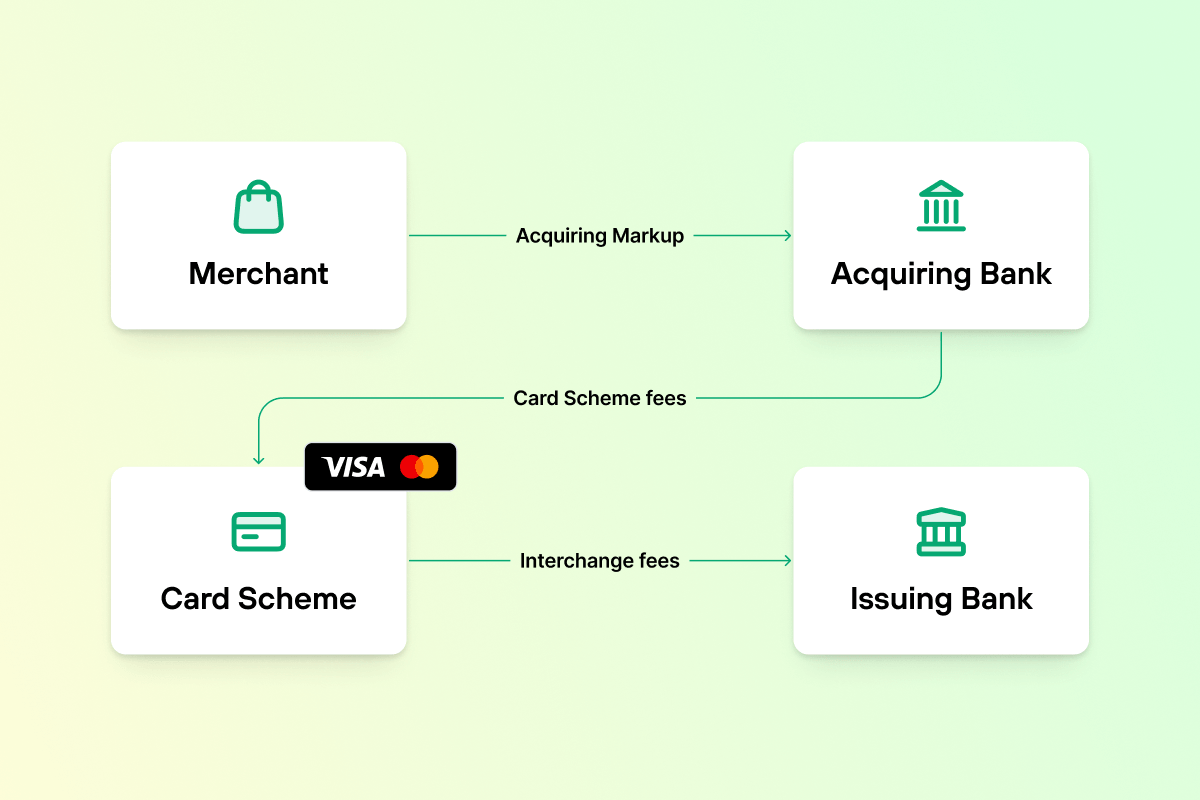
- Every card transaction carries three cost layers: interchange, scheme fees, and the acquirer markup (the only one that can be negotiated)
- Rates vary significantly by market and card type. EU/EEA consumer cards are capped at 0.20% (debit) and 0.30% (credit) for domestic card-present transactions. US consumer credit runs from roughly 1.15%–1.18% to 3.15%, depending on network
- Merchants can lower their effective rate by optimizing card mix, using local acquiring, submitting Level 2/3 data on commercial cards, enabling network tokenization for CNP transactions, and keeping transaction data clean to avoid interchange downgrades
What are interchange fees?
Interchange fees are the transfer fee an pays to the every time a customer completes a card payment. Merchants pay this cost indirectly – it flows from the acquiring bank to the to the issuing bank, bundled inside the overall merchant discount rate.
The fees exist to compensate issuing banks for the real costs they carry:
- Card issuance and maintenance
- Fraud risk
- Interest-free grace period extended to credit cardholders
- Guarantee of payment to the merchant
Without that compensation, banks have less incentive to issue cards and honor card-based payments at scale.

Interchange fees vary based on card type, transaction method, merchant category, and the region where the transaction occurs. A basic debit card tapped in-store and a premium rewards credit card used for an online purchase can carry rates that differ by a factor of ten or more. That range reflects the different risk profiles and issuer costs associated with each transaction type.
How interchange fees work: Who pays, who sets them, who earns
When a customer pays with a card, several parties exchange value in the background before the merchant receives funds. The merchant gets the transaction amount minus processing costs; the issuing bank earns the interchange fee for its role in the transaction.
Here is the sequence:
Step 1 – Transaction initiation. The customer presents a card at checkout. The merchant's payment terminal or payment form sends the transaction data to the acquiring bank.
Step 2 – Authorization request. The acquiring bank forwards the transaction to the card network (Visa, Mastercard, Amex), which routes it to the issuing bank.
Step 3 – Authorization decision. The issuing bank checks the cardholder's account, confirms available funds or credit, and returns an approval or decline through the network.
Step 4 – Settlement. At end of day, the merchant submits the batch of authorized transactions. The acquiring bank sends these to the card network for settlement. The network routes each transaction to the correct issuing bank.
Step 5 – Interchange transfer. The card network transfers funds to the acquiring bank minus the interchange fee. The issuing bank receives the interchange fee as compensation for bearing the transaction risk and funding the payment guarantee.
Step 6 – Merchant payout. The acquiring bank deposits the funds into the merchant's account, minus its own markup and scheme fees. What the merchant receives is the transaction amount less the full merchant discount rate.
How interchange fees are set
Card networks set interchange rates – the percentage (and sometimes fixed fee) applied to a transaction, not the fee itself. Visa and Mastercard publish updated schedules twice a year – April and October. Amex and Discover operate differently: Amex acts as both network and issuer in many markets and does not publish rates with the same transparency.
The factors that determine which rate applies to a given transaction:
- Card brand – Visa, Mastercard, Amex, and Discover each maintain their own rate schedules.
- Card type and tier – consumer debit, consumer credit, prepaid, business, corporate, and premium rewards tiers all carry different rates. Premium cards like Visa Infinite and Mastercard World Elite carry higher interchange than standard consumer cards.
- Transaction method – card-present transactions (chip, contactless) carry lower rates than card-not-present (online, phone order) because in-person authentication reduces fraud risk.
- Merchant category code (MCC) – the business type assigned by the acquiring bank. Certain MCCs qualify for reduced rates: charities, utilities, government payments, and some streaming and travel categories in specific markets.
- Consumer vs. commercial cards – commercial and corporate cards are exempt from regulatory caps in most markets and carry higher rates than consumer cards.
- Geography – domestic transactions (card issued in the same country as the merchant) are generally cheaper than cross-border transactions.
- Security protocols – 3D Secure authentication, EMV tokenization, and chip-based transactions can qualify for lower rates or CNP incentives (see the cost-reduction section below).
Core insight: The merchant pays, the card network sets the interchange rate, and the issuing bank earns the fee. Regulation decides how wide the gap between those three roles can get – tightly bounded in the EU, wide open in the US.
How much are interchange fees in 2026?
Here is what typical interchange looks like across the major markets and card types, based on Visa's ( and ) and published rates.
| Card network / market | Rate range | Regional restrictions |
| Visa & Mastercard – EU/EEA consumer, domestic | 0.20% to 0.30% | Regulated/Capped – consumer cards capped under the EU Interchange Fee Regulation (IFR) |
| Visa/Mastercard – US regulated debit (Durbin) | 0.05% + $0.21 | Regulated/Capped – applies only to debit cards from issuing banks with $10B+ in assets |
| Visa – US consumer credit | 1.18% + $0.05 to 3.15% + $0.10 | Unregulated – credit interchange has no federal cap in the US |
| Mastercard – US consumer credit | 1.15% + $0.05 to 3.15% + $0.10 | Unregulated – credit interchange has no federal cap in the US |
| American Express – US | 1.43% + $0.10 to 3.30% + $0.10 | Independent pricing – Amex operates as both network and issuer; not bound by standard open-loop caps |
Core insight: Interchange in 2026 spans from 0.05% + $0.21 (US regulated debit) to 3.15% + $0.10 (US non-qualified credit). In the EU/EEA, both networks are also capped identically, at 0.20%–0.30%. The market and card type determine which end of the range a merchant lands on.
Interchange fees by region: EU, UK and US
Interchange regulation varies sharply by geography. Some markets cap what card networks can charge; others leave rates to open-market competition. That difference is the single biggest driver of how much a merchant actually pays.
European Union and European Economic Area (EU/EEA)
The caps consumer card interchange across the EEA at 0.20% for debit and 0.30% for credit. Two exceptions affect merchants with cross-border or B2B volume.
First, commercial and corporate cards are exempt from the caps. Business credit cards from Visa and Mastercard carry rates starting around 1.30% and rising to 2.00% or higher for e-commerce transactions – well above the consumer card ceiling.
Second, non-EEA-issued consumer cards transacting at EEA merchants face interregional rates that depend on how the card is used. In-store, the rate matches domestic: 0.20% debit, 0.30% credit. Online, it jumps to 1.15% debit and 1.50% credit – the same underlying regulation, but the card-not-present rate is roughly five times higher. Merchants selling online to customers with non-EEA-issued cards should budget for the higher online rate.
United Kingdom (UK)
Following Brexit, the UK's version of the IFR applies only to UK domestic consumer card transactions. The same 0.20% debit and 0.30% credit caps hold for UK-issued cards at UK merchants.
For cross-border transactions – a UK-issued card at an EEA merchant, or an EEA-issued card at a UK merchant – the interregional caps apply: 0.20% (debit) and 0.30% (credit) card-present, 1.15% (debit) and 1.50% (credit) card-not-present. Merchants operating across both the UK and EU markets should account for this gap when forecasting processing costs on their online traffic.
United States (US)
The US regulatory environment is split between debit and credit. Debit card interchange is regulated under the (part of the Dodd-Frank Act), implemented through the Federal Reserve's Regulation II, for issuing banks with consolidated assets of $10 billion or more. Those institutions are subject to a cap of 0.05% + $0.21 per transaction. Smaller community banks and credit unions are exempt and can earn higher interchange on debit transactions.
Credit card interchange fees in the US are unregulated. Rates are set independently by each network, typically ranging from around 1.17% + $0.05 for standard consumer credit to 3.15% + $0.10 for non-qualified transactions.
Core insight: The EU regulates both debit and credit interchange tightly. The US regulates only debit, leaving credit to open-market competition. That single structural difference explains most of the rate gap between the two markets.
Total card processing cost: Interchange, scheme fees, and acquirer markup
The total a card payment is the sum of three separate charges.
Interchange fee – flows to the issuing bank. It’s typically the largest component that is set by card networks and applied uniformly – non-negotiable for the merchant.
Scheme fee – goes to Visa or Mastercard for operating the network infrastructure connecting issuers and acquirers. It covers assessment fees, authorization fees, and cross-border fees and is also set by card networks – non-negotiable.
Acquirer markup – the margin charged by the acquiring bank or payment service provider (PSP) for processing services. This is the only one of the three a merchant can negotiate, typically based on transaction volume.
Add the three together and the result is the merchant discount rate (MDR) – the total processing cost that shows up on a merchant's statement.
Interchange (IC)++ vs. blended pricing
How those three components are presented to merchants varies by pricing model.
Interchange++ pricing (also known as IC++ or interchange plus plus) shows each component separately: the exact interchange rate, the exact scheme fee, and the acquirer's markup on top.
The total is transparent but variable – interchange shifts by card type and transaction method, so per-transaction cost cannot be predicted in advance.
IC++ suits higher-volume merchants who want full cost visibility and can use the data to optimize card mix and routing.
Blended pricing collapses all three into a single flat rate – for example, 2.9% + a fixed fee per transaction. The cost is predictable and the bill is simple to reconcile.
The trade-off is that savings from lower-interchange transactions are absorbed by the provider rather than passed through to the merchant.
Blended pricing suits early-stage businesses where simplicity outweighs cost visibility.

Core insight: Total card processing cost is made up of interchange, scheme fees, and the acquirer markup – the only one of the three that's negotiable. IC++ pricing shows all three separately; blended pricing hides them behind one flat rate.
How to calculate interchange fees
Interchange fees are calculated as a percentage of the transaction amount, sometimes with a fixed per-transaction component added.
Interchange fee = Transaction amount × interchange rate (%) + fixed fee (if applicable)
For instance, a customer pays €500 for a software subscription using an EEA-issued Visa consumer credit card, card-present. The IFR cap applies: 0.30%.
Fee: €500 × 0.30% = €500 × 0.003 = €1.50
The merchant's acquiring bank pays €1.50 in interchange to the customer's issuing bank on this transaction, before scheme fees and the acquirer's own markup are added.
How to lower your interchange costs
Interchange rates cannot be negotiated directly. What merchants can do is optimize which rate category their transactions qualify for, reduce the volume of high-cost card types, and ensure their transaction data is clean enough to avoid downgrades.
Push debit over credit
Debit card transactions carry materially lower interchange in every market. In the EU, the spread between debit (0.20%) and credit card interchange rates (0.30%) is relatively small in absolute terms, but on high volume it adds up. In the US, regulated debit (0.05% + $0.21) is dramatically cheaper than consumer credit (roughly 1.17%–3.15%).
Where customers have a choice, surfacing debit as the default payment option shifts the mix in a cost-effective direction.
For credit transactions merchants can't shift to debit, some jurisdictions allow surcharging – adding a fee at checkout specifically for paying with credit, to recover the interchange cost directly from the customer rather than absorbing it.
Surcharging rules vary significantly by country and card network, and some regulators cap the surcharge at the actual cost of acceptance, so this needs a legal check before implementation in any given market.
Use local acquiring
Domestic transactions attract lower interchange rates than cross-border transactions in most markets. Local fixes this at the source: an EEA-based acquirer for EU transactions, a UK-based acquirer for UK transactions.
On top of that, selects the best-performing provider for each transaction automatically, so merchants don't have to manage this split manually as their provider setup grows more complex.
Enable network tokenization for card-not-present transactions
Network tokenization replaces raw card numbers with a token unique to one device or merchant. A stolen token is useless anywhere else, so tokenized transactions carry lower fraud rates and higher authorization rates than transactions using raw card data.
reports a 39.4% lower fraud rate and a 4.8% lift in authorization rates for tokenized transactions compared to raw card numbers.
On , tokenization alone earns a 0.05% reduction in the interchange fee; combining it with the Digital Commerce Authentication Program (DCAP) earns up to 0.15% off.
For merchants running multiple PSPs, token portability matters as much as token issuance – a token tied to one provider is only as useful as that provider's role in the stack. A provider-agnostic stores tokens independently of any single PSP, so merchants can add or switch providers without losing stored credentials or re-collecting card data from customers.
Use Address Verification Service (AVS) to prevent chargebacks
A chargeback on a transaction means losing both the transaction amount and the interchange fee paid on it. Merchants with elevated chargeback rates can also be reclassified as higher-risk, which may trigger higher-cost interchange programs.
AVS verifies the cardholder's against the issuer's records during authorization, reducing fraud-related chargebacks. To use it, submit the billing address alongside the authorization request and build a response logic based on match outcomes.
Settle transactions promptly and submit complete data
Late settlement – beyond the card network's standard window, typically 24 hours – can trigger an interchange downgrade to a higher-rate fallback category. Missing or incomplete transaction data has the same effect. Both are within the merchant's control and represent straightforward operational improvements that prevent avoidable cost increases.
Explore alternative payment methods
Bank transfers, digital wallets with direct bank connectivity, and other bypass card interchange entirely. For merchants where a meaningful share of customers is open to non-card payment options, offering them at checkout shifts volume to lower-cost rails. The right mix depends on the merchant's market and customer base.
Core insight: Lower interchange comes from pushing debit, using local acquiring and routing, tokenizing card-not-present transactions, using AVS, settling promptly with clean data, and offering non-card payment methods.
Keep your interchange costs in check
Interchange is one of those costs that feels fixed until you examine it closely. The rate schedules are published, the rules are documented, and the levers are known – card mix, authentication quality, data completeness, local acquiring, and transaction method. What varies between merchants is how systematically those levers are pulled and which payment infrastructure is used.
Solidgate is a payment orchestration platform that connects merchants to 100+ acquirers and through one integration, with , , automatic fallback, network tokenization, and account updater built in to reduce failed payments and keep approval rates high.
If you want to check your current payment setup and know how to improve it, .
10x payment processing growth in 3 years
How Zeely lifted approval rates by 8% and cut risk metrics by 40% with Solidgate
Frequently asked questions
Interchange fees are transaction fees charged between banks for the processing of credit and debit card transactions. They are typically paid by the merchant's acquiring bank to the cardholder's issuing bank for each transaction.
Interchange fees are paid by the merchant's acquiring bank to the cardholder's issuing bank. In practice, merchants absorb this cost indirectly through the merchant discount rate charged by their payment provider – interchange is the largest component of that rate.
Card networks – Visa, Mastercard, Amex – set interchange fees based on card type, transaction method, merchant category code, geography, and security protocols used. Visa and Mastercard publish updated rate schedules in April and October each year.
Network-set interchange fees and scheme fees are not negotiable for merchants. The acquirer markup – the third component of the merchant discount rate – can be negotiated, typically based on transaction volume.
It depends on the market and card type. In the EU, consumer card interchange is capped at 0.20% (debit) and 0.30% (credit) for domestic card-present transactions. In the US, consumer credit interchange typically ranges from around 1.17% + $0.05 to 3.15% + $0.10 for non-qualified transactions. Regulated debit in the US runs at 0.05% + $0.21 for large-bank-issued cards.
Interchange fees are the transfer fee paid from the acquiring bank to the issuing bank – set by card networks, non-negotiable. The merchant discount rate (MDR) is the total cost a merchant pays to their acquiring bank or payment provider, which bundles interchange, scheme fees, and the acquirer's own markup. Interchange is typically the largest single component of the MDR but is just one part of it.
A US court gave preliminary approval to a settlement that will lower credit card interchange fee for merchants, once it's finalized. Standard consumer credit rates would be capped at 1.25%, down from what many merchants pay today.
Merchants would also gain the right to decline expensive premium cards or add a surcharge for credit card payments – something the old rules didn't allow. Debit rates aren't affected, and none of this takes effect until the court gives final approval.