Chargeback fees
What are chargeback fees?
Chargeback fees are the administrative charges an acquirer or payment processor bills a merchant each time a is filed against them. The fee is fixed in the merchant agreement, applies per dispute, and sits on top of the disputed transaction amount.
The fee covers the cost of handling the case: pulling transaction records, moving the claim between the and the , and debiting the . It's billed the moment the issuing bank raises the dispute, before anyone knows how the case ends, so it applies even to disputes the merchant later wins. Terms vary by processor, but the fee is typically non-refundable regardless of the outcome. That makes it a fixed cost of receiving a dispute rather than a penalty for losing one.
Key facts
- Charged by: the acquirer or , under the terms of the merchant agreement
- Charged per: individual chargeback, not per transaction and not as a monthly total
- Triggered when: the issuing bank files the dispute, before any outcome is known
- Refundable: typically not, even after a successful
- Stacks with: the reversed transaction amount, the original , and the cost of any goods or services already delivered
- Escalation fees: and arbitration each carry separate fees set by the card scheme, not by the acquirer
How the total cost is calculated
The fee itself is a flat contractual amount, so the arithmetic that matters is the full cost of a single chargeback:
Total cost = disputed amount + chargeback fee + original transaction fee + cost of goods or services delivered + any escalation fees
Each element behaves differently. The disputed amount comes back if the merchant wins representment; the chargeback fee does not. The original processing cost is already spent, and delivered goods or consumed subscription time are unrecoverable in most disputes. Escalation adds a second layer: pre-arbitration and arbitration trigger scheme-set fees charged separately from the acquirer's fee, and the losing side pays them.
A third layer applies once volume becomes a problem. When a merchant's crosses the scheme thresholds behind , enrollment adds a further per-case charge on top of the standard fee.
What affects the fee amount
- Merchant agreement: the per-dispute rate is negotiated with the acquirer and written into the contract
- Risk classification: and associated with elevated dispute volume are priced higher
- Chargeback rate: crossing a moves the account into monitoring programs with their own fee schedule
- Region and scheme: cross-border cases and different card networks carry different handling costs
- Escalation stage: each step past the first chargeback adds a scheme-set fee
How to reduce chargeback fees
Because the fee lands the moment a dispute is filed, the lever is dispute volume rather than the fee itself. Merchants typically work on:
- Deflection before filing. Prevention alerts and let a merchant refund a transaction before the issuer converts it into a chargeback, which avoids the fee entirely.
- A recognizable billing descriptor. Unclear are a common cause of , where the cardholder disputes a charge they simply don't recognize.
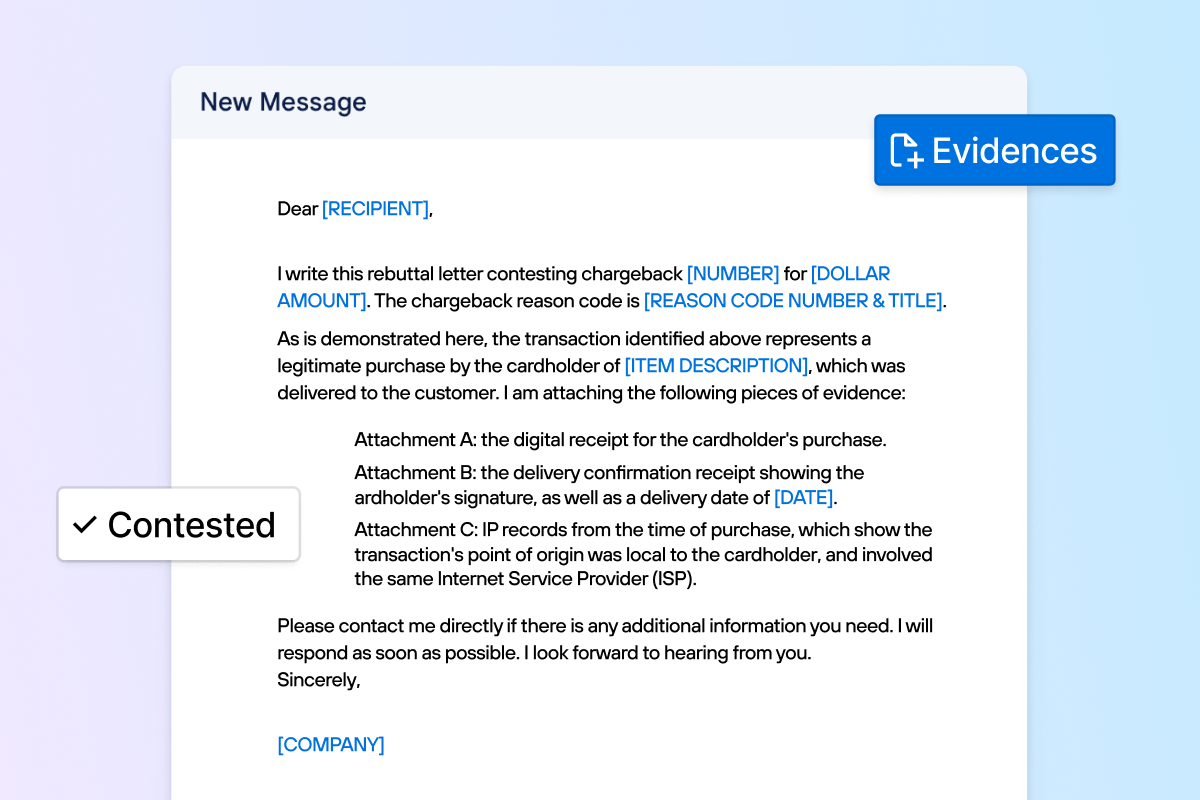
- Selective representment. Winning returns the disputed amount but not the fee, so cases with weak can cost more to fight than to write off.
- Staying under monitoring thresholds. Keeping the chargeback rate below scheme limits avoids the program fees that get layered on top of the standard per-dispute charge.